Ai-powered investment decision

Vision

Our vision

Understand the drivers of financial markets

In a complex environment with contradictory signals, it is crucial to identify relevant variables to rationalize investment decisions.

Ai For Alpha develops AI-based quantitative analyses to help investment professionals understand market regimes and assess allocation and risk exposures.

Connecting AI research with investment decision support

Approach

Our approach

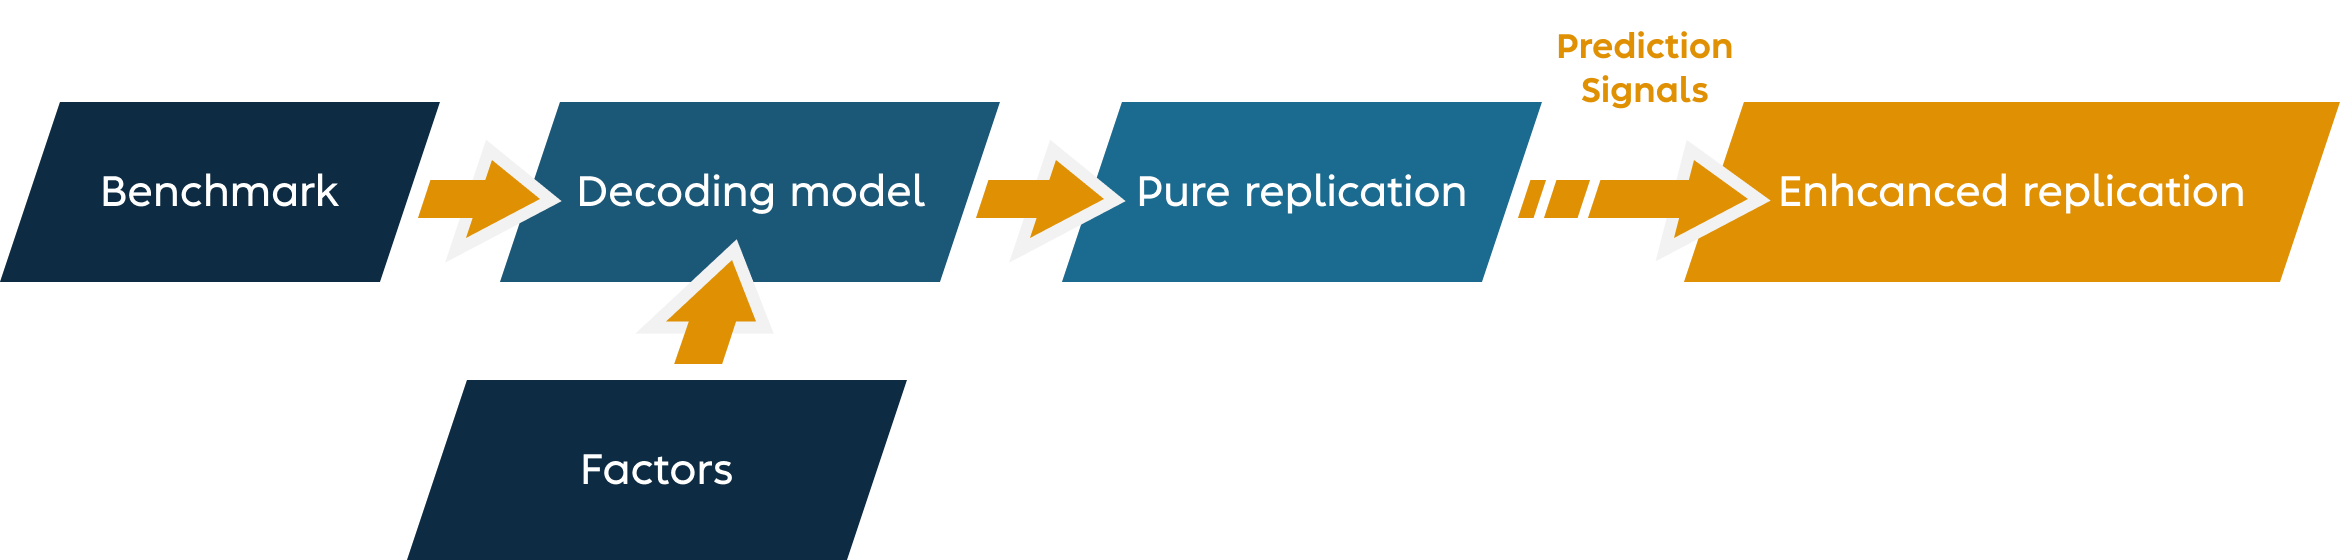
Decoding uses historical valuations to estimate the factor exposures of an investment strategy.

The model constructs a futures-based portfolio designed to track a reference benchmark. Replication is subject to data, model and implementation limitations.

Ai For Alpha licenses Decoding models and portfolios to professional investors for futures-based strategy analysis and decision support.

Solution

Ai For Alpha provides quantitative analyses and decision support concerning futures contracts, and licenses Decoding models and portfolios. The futures-based replication framework includes Pure, Tactical and Hyper Decoding.

This website presents the firm and its research. It provides no personalised advice, return target or promise of performance. Any personalised advice is provided outside the website under a separate written agreement. Regulatory & Risk Disclosures.

Futures involve leverage and substantial risk of loss. Losses may exceed the funds initially committed and may lead to margin calls.

Pure decoding

Benchmark replication
  • CTAs
  • Risk Parity

Tactical decoding

  • Global Balanced Funds
  • Global Hedge Funds

Hyper decoding

Unconstrained Decoding
  • Risk-Off CTA
  • Liquid Private equity

Tactical Decoding

Tactical Decoding combines benchmark replication with predictive signals to analyse and adjust futures exposures. Outcomes depend on market conditions, data and model assumptions.

Pure replication Tactical position Enhanced replication
Equity 30.0% 2.0% 32.0%
Bond 49.0% 3.0% 52.0%
Commodity 7.0% -0.5% 6.5%
Fx vs. USD -60.0% -10.2% -70.2%
Illustrative Replication example

Illustrative Comparison

Fictitious data illustrate a comparison between a model strategy and a reference benchmark.
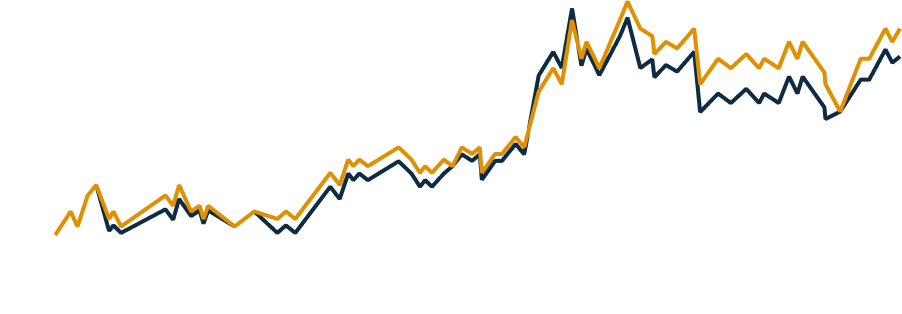
Illustrative comparison using fictitious strategy and benchmark data

- Tactical Decoding     - Benchmark

Illustrative chart using fictitious data only. Dates and values do not represent actual or backtested performance. This is not a forecast or a promise of future results.

Value proposition for investors

High correlation with the benchmark

Decoding seeks high correlation with a reference benchmark through futures-based replication.

Risk diversification

Replication can reduce dependence on a single asset manager. Leverage, margin and model risks remain.

Liquidity

Strategies based on liquid futures

Transparency

Investors have access to the daily allocation and performance attribution on their portal

Cost-efficient

Futures-based replication is designed for cost-efficient implementation.

Clients & partners

Our clients are

Institutional Investors

Investment Banks

Asset Managers

Private Banks

Awards

LBPAM Innovation Trophy
Ai For Alpha won the LBPAM Innovation Trophy in the FrenchTech Category in 2025.
eit
Ai For Alpha has received funding from the European Institute of Innovation and Technology (EIT).
This body of the European Union receives support from the European Union's Horizon 2020 research and innovation program.
Finance Innovation
Ai For Alpha has received the worldwide Finance Innovation label in 2020.
women_tech
Only French fintech to be awarded the 2023 Women TechEU Award.
microsoft
Ai For Alpha has been selected by the Microsoft for Startups Founders Hub.
ECML PKDD
Ai For Alpha won the Best Paper Award at the ECMLPKDD 2024 MIDAS workshop.

Decoding Technology

Ai For Alpha's Decoding technology estimates investment strategy exposures from historical valuations. Machine learning is used to construct a futures-based model portfolio designed to track a reference benchmark.
The framework can be adapted to different factors, benchmarks and model constraints.

Factors

Ai For Alpha analyses factors across asset classes and investment strategies to estimate replication exposures.

Decoding Models

The Ai For Alpha Decoding model infers the dynamic exposure to each factor in order to seek high correlation with the benchmark.

Allocation

The weights are reallocated daily to target the specified volatility while tracking the benchmark.

Enhanced Decoding

Predictive signals help assess deviations from benchmark replication and alternative futures exposures.
value_proposition
The prediction model analyses multiple market factors to estimate signals and compare allocation scenarios.
Technical indicators
Market Breadth, Investors Positioning
Price Indicators
Risk adjusted returns, Volatilities, Momentum
Risk Perception
Implied Volatilities, Credit Spreads
Macroeconomic factors
Growth, Inflation, Interest Rates’ evolution, Central Banks monetary decisions
Financial Metrics
Earnings, Sales, Valuation Multiples

Augmented Intelligence

Augmented Intelligence

Leveraging on Ai potential, investment decisions take on a more powerful dimension.

An Algorithm Trained Over Time

An Algorithm Trained Over Time

Our incremental model is continuously being trained and developed with the most recent market data.

Strategic Use of Data

Strategic Use of Data

Macroeconomics, interest rates, government decisions, inflation and company valuations: Ai for Alpha analyzes hundreds of drivers by testing their prediction power on specific markets.

Infer Daily Investment Decision / Allocation of Market Environment

Infer Daily Investment Decision / Allocation of Market Environment

Proprietary models estimate allocation weights based on data-driven signals and specified model constraints.

Anticipating Market Risks

Anticipating Market Risks

Predictions are estimates and may not materialise. Our models examine relationships between market factors and financial regimes, subject to data and model limitations.

Explainable Data

Explainable Data

Our approach is fully transparent. We apply our “feature importance” methodology to extract key drivers that impact portfolio allocation at any time.

Team

Management

Chief Executive Officer

Béatrice has more than 20 years of experience in financial markets. She held various management positions in structuring departments in top tier US and European banks (JP Morgan, Deutsche Bank, Société Générale). Béatrice graduated from the engineering schools Ecole Polytechnique and ENSAE. She holds two masters’ degrees, in financial mathematics from LPSM (laboratoire de probabilités statistique & modélisation) and in finance from the London School of Economics.

Main Team Members

Research Adviser

Eric has held leadership roles as head of quants at Goldman Sachs and Natixis. He founded Pricing Partners, a startup focused on pricing complex financial products, which was later acquired by Refinitiv (formerly Thomson Reuters).

Ranked among the top 1% of researchers on SSRN (Social Science Research Network), Eric holds a global ranking within the top 10 among 500,000 researchers, with over 100 published papers and articles.

A graduate of Polytechnique, Eric also completed degrees at ENSAE and the London School of Economics. He holds three PhDs in Economics, Mathematics, and Computer Science, along with two master’s degrees, including one in AI from Dauphine and ENS Ulm. Additionally, he achieved the prestigious Agrégation in Mathematics.

Solutions Adviser & Chief Compliance Officer

Jean-Jacques has over 15 years' experience in investment management and research. During this time, he has designed various cutting-edge trading models for numerous asset classes.

Jean-Jacques began his career at Crédit Agricole Asset Management in 1999 as a risk manager and worked as a fund manager for Natixis AM and Finaltis. He founded a fintech called Riskelia, which was acquired by Homa Capital, where he was CIO and created several quantitative funds.

Jean-Jacques received the Lipper Award in 2019 for the best Futures fund managed over three years. He is a regular guest on Financial TV. He is an alumnus of the CentraleSupélec engineering school and holds a CFA.


Strategic Business Introducer

Thomas has over 20 years of experience in capital markets, specializing in structured products, derivatives, and Quantitative Investment Strategies (QIS).

He began his career covering Latin America at Commerzbank and Crédit Agricole in London and New York, and then spent 15 years at Société Générale promoting investor solutions to U.S. and Latin American institutions.

Thomas is an alumnus of Dauphine University and Brandeis University.


Quantitative Researcher

Ethan previously worked as a Quant/Data Scientist at AlphaBeta and as an Assistant Trader at Natixis CIB. He holds an MSc in Data Science from CentraleSupélec and an engineering degree in quantitative finance from ESILV.


Quantitative Researcher

Chamyl previously worked as a Data Scientist at Natixis CIB. He holds an engineering degree with a specialization in quantitative finance from ECE Paris.